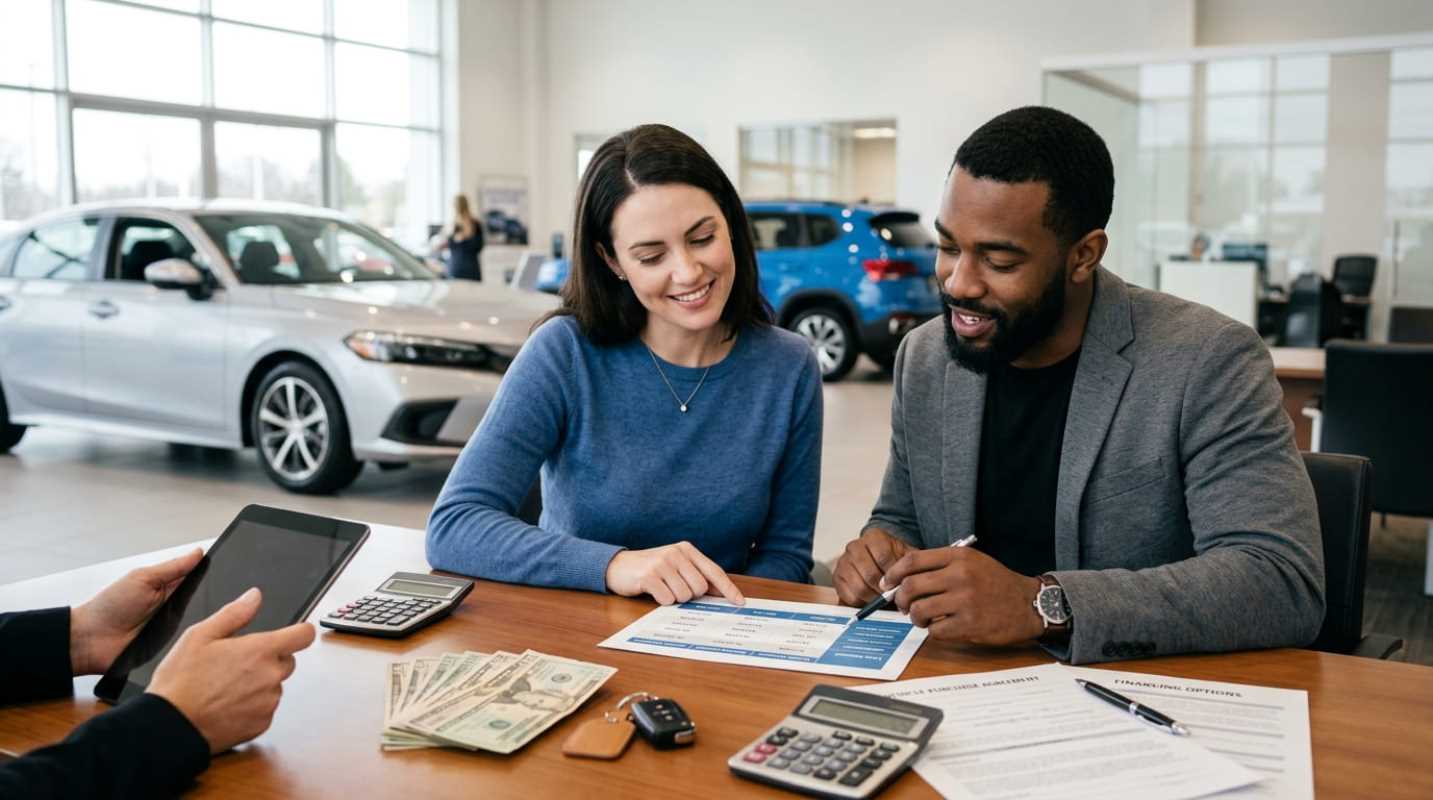
You spent weeks researching vehicles, test drove your favorite model, and agreed on a purchase price with the salesperson. Then you walk into the finance office, sit in front of the loan manager, and watch the total cost climb. Suddenly, the bottom line is thousands of dollars higher than the number you negotiated.
Have you been there?
The sticker price on a car is rarely what you end up paying. Dealerships make a huge portion of their profits not on the vehicle itself, but in the finance and insurance office. With auto loan rates remaining elevated, dealers often use hidden fees and marked-up loan terms to pad their margins. Learning how to identify these charges gives you the power to push back, negotiate effectively, and keep your hard-earned money where it belongs.
The Hidden Price Tag and Understanding Auto Loan Fees
When you finance a vehicle, the paperwork can feel like a lot. There are stacks of contracts, fine print, and itemized lists of numbers. Dealers count on buyers feeling too tired or intimidated to question extra line items.
The first step in protecting yourself is knowing which fees are mandatory and which ones are pure dealer profit. Legitimate costs come from the government or the vehicle manufacturer. These include state sales tax, local vehicle registration costs, and state title transfer fees. Another mandatory charge is the destination fee, which covers shipping the car from the factory to the dealership. This factory freight charge appears on the original window sticker, and the dealer cannot change it.
Everything else on the contract is generally discretionary, padded, or optional. When you take the time to review every line item before signing, you can easily save two to three thousand dollars on an average transaction.
Decoding Loan Origination Charges and Administrative Costs
Loan origination fees are common when you buy a house, but they should raise red flags on a standard auto purchase. An origination fee represents what a lender charges to process, underwrite, and fund your loan.
Although some online direct lenders and secondary credit institutions charge loan processing fees, traditional auto loans from credit unions and major banks rarely do. If you spot an origination charge, acquisition fee, or processing fee on a standard retail purchase, ask who is charging it.
• Lender fees: Subprime lenders sometimes attach administrative fees for borrowers with lower credit scores. If you have solid credit, you should never accept a loan that includes an upfront origination charge.
• Dealer administration fees: Dealerships sometimes invent their own processing charges. They might call it a loan set-up charge, customer processing fee, or administrative service fee. This is often just extra dealer markup dressed up to look like an official banking expense.
If the finance manager claims the charge is standard, ask them to waive it. If they say the lender requires it, ask to see the official lender rate sheet or tell them you want to apply with an alternative bank that skips administrative fees entirely.
The Reality of Dealership Financing Costs
The finance office has several quiet ways to extract extra cash from your loan agreement. One of the biggest profit centers is the interest rate markup, often called dealer reserve.
When a dealership runs your credit, the financing institution gives them an approved wholesale rate, known as the buy rate. Like, the bank might approve your loan at 6.0%. But state laws usually permit the dealership to mark up that rate by 1.0% to 2.5% and keep the spread as a commission. If they bump your rate to 8.0% on a $40,000, five-year loan, that markup costs you over $2,200 in extra interest over the life of the loan.
Beyond interest rate padding, watch out for documentation fees. Billed as the cost of handling sales contracts and filing paperwork, the actual behind-the-scenes administrative cost runs around $25 to $75.¹ Yet dealerships charge hundreds, or even thousands, for this service. In capped states like California, doc fees cannot exceed $85, but in uncapped states like Florida, dealers routinely charge $1,000 to $1,200 or more.³
Dealers will tell you that state rules prevent them from waiving the doc fee. That is technically true in many jurisdictions because they must charge every buyer the same fee to avoid discrimination complaints. But nothing stops them from reducing the sales price of the car by that exact amount to offset the charge.
You should also watch for dealership add-ons that get rolled into your total loan balance
• Vehicle prep and inspection fees: Dealers often add $500 to $1,500 for cleaning the car and checking fluid levels. Automakers already reimburse franchised dealers for pre-delivery inspections. Paying this fee means paying twice.
• Nitrogen tires and VIN etching: Dealers charge $100 to $250 for nitrogen, even though regular air is already 78% nitrogen. They also charge up to $500 for window VIN etching, which you can do yourself with a $20 kit.
• Overpriced GAP protection: Guaranteed Asset Protection covers the difference between your car's market value and what you owe if the car gets totaled. Dealerships routinely charge $900 to $1,500 for GAP. You can buy the same coverage through your insurance company or credit union for $300 to $500.
Regulatory agencies like the Federal Trade Commission have actively penalized dealer groups for slipping deceptive add-ons and surprise fees into consumer contracts.² Knowing your rights helps you push back before these charges get buried in your monthly payments.
Prepayment Penalties and Early Exit Fees
What happens if you want to pay off your vehicle early? Maybe you receive a bonus at work, or maybe you decide to refinance next year. You might assume your lender will welcome early payment, but that depends on the terms in your contract.
Some auto loans include prepayment penalties. Lenders make their money on the interest accrued over time. When you pay off a balance ahead of schedule, the lender loses out on those planned interest payments. To make up for that lost revenue, certain finance companies charge an early exit fee.
To protect yourself, check your retail installment contract for how interest is calculated
• Simple interest loans: This is the consumer-friendly standard. Interest accrues daily based on your remaining principal balance. If you pay early, you save money on interest, and there is no penalty.
• Precomputed interest loans: These loans calculate the total interest for the entire loan term on day one. Even if you pay off the balance within two years, you may still owe the full interest amount originally scheduled for all five years.
Always ask the finance manager directly: "Is this loan simple interest, and is there any fee or penalty for paying it off early?" Verify that the prepayment box on your contract states you will not face a fee.
Having the right financing resources in place gives you an immediate advantage when you walk onto a car lot.
Final Checklist for Protecting Your Wallet Before You Sign
Walking into a dealership prepared is the single best way to avoid junk fees and financing markups. Use these action steps to keep your deal clean
• Secure outside pre-approval: Apply for a loan at your local credit union or bank before visiting a showroom. When you bring your own pre-approved rate, the dealership cannot quietly mark up your interest rate.
• Negotiate the out-the-door price: Never negotiate around a target monthly payment. Dealers use long loan terms to hide thousands of dollars in fees while hitting your monthly payment target. Demand an itemized out-the-door price sheet before discussing financing.
• Inspect the itemized financing contract: Before you sign, review the itemization of the amount financed on your contract. Look at every single dollar between the vehicle price and the total balance. If an optional product like GAP or paint protection is listed, tell them to take it off.
• Be willing to walk away: If a dealership insists that mandatory dealer prep fees or expensive protection packages cannot be removed, stand up and leave. There are plenty of other dealerships ready to earn your business without the games.
Sources:
1. Everything You Need to Know About the FTC Doc Fee Crackdown
https://kgidealersolutions.com/resources/everything-you-need-to-know-about-the-ftc-doc-fee-crackdown
2. The Ultimate Guide to Dealer Fees
https://www.carwhere.com/guides/dealer-fees
3. Dealer Documentation Fee Explained
https://otdcheck.com/blog/dealer-documentation-fee-explained
*This article on CarDivide is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*